I Stopped Funding My Family and Uncovered My Husband’s Missing Money
The blue graduation invitation is still stuck to my refrigerator with a little magnet shaped like a strawberry. My granddaughter, Lily, mailed it herself, writing Please come, Grandma across the bottom in purple ink. I already bought a pale green dress and had the hem shortened. Then my son, Nathan, calls and tells me it would be better if I didn’t attend. He says Lily doesn’t need family tension on her special day. I ask what tension he’s talking about, and he reminds me of the mortgage payment I refused to make for him last month.
Nathan is my oldest. His sister, Brooke, lives about forty minutes away, and my youngest, Colin, rents an apartment downtown. Their father, Walter, and I spent thirty-eight years building a fairly ordinary life together. He repaired commercial refrigeration units, and I handled payroll for a small construction company. When Walter died, he left me a paid-off house, retirement savings, and a little notebook where he’d carefully recorded every major expense we’d ever made. I’m seventy now, and I still use that notebook to keep track of things. Somehow, my children have started treating those savings as if they’re a family checking account.
It begins with little favors. A utility bill here, a car payment there. Then Nathan needs help with his landscaping business. Brooke wants money to renovate her kitchen before hosting Thanksgiving. Colin needs a deposit for a bigger apartment. I help all three because they’ve always been my world. But once I start saying no, the phone calls practically disappear. Last Christmas, nobody even asks where I’m spending the holiday. I eat dinner with my neighbor, Ruth, and tell her the kids are busy. It sounds less embarrassing that way.
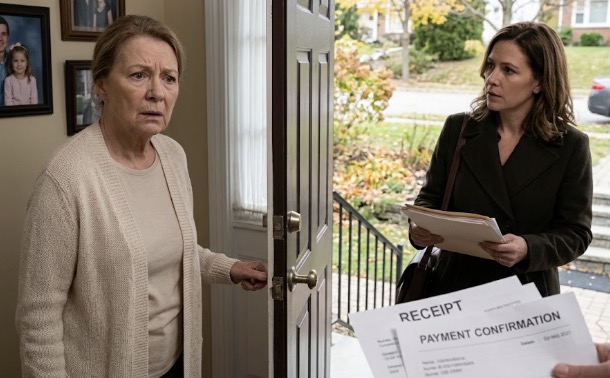
Two days after Lily’s graduation, Ruth comes over while I’m washing the breakfast dishes. She says there’s a woman waiting on my porch who insists she needs to speak with me about Nathan. The woman introduces herself as Denise Walker and holds a manila envelope against her chest. She’s nervous enough that she keeps rubbing one thumb across the envelope’s torn corner.
“I work in the office that handles the payments for your son’s business,” she explains. “I think you should see something before he asks you for any more money.”
I invite her inside. She spreads six payment receipts across my kitchen table. Every one carries my name. And when I look at the dates, I realize Nathan has been using something I gave him years ago for a purpose I never agreed to.
Denise points to the earliest receipt. The payment is credited to an account associated with Walter’s old equipment business, which Nathan was supposed to have closed after his father died. But the account is still active, and the invoices show regular payments coming from it. Then Denise shows me a second page, marked with Nathan’s handwritten instructions…
The instructions are written on a plain sheet of yellow paper.
I recognize Nathan’s handwriting immediately. He forms his capital letters with a slight backward slant, just like his father used to.
At the top, he has written the account number for Walter’s old equipment business.
Underneath are directions for applying incoming customer payments.
Most go toward legitimate outstanding bills.
But three entries don’t belong there.
They’re marked as reimbursements to me.
I turn the page over, hoping there’s an explanation.
“Why would he put my name on money I never received?”
Denise takes a folded statement from her envelope.
“That’s what concerned me.”
She explains that her company provides bookkeeping support to several local businesses, including Nathan’s landscaping operation. While reconciling older accounts, she notices payments from customers who still owe Walter’s former business money.
The business stopped operating after Walter died, but several customers have continued making installment payments for equipment purchased years earlier.
Nathan has been managing those collections using authority I gave him when Walter became ill.
I remember signing the paperwork.
It allowed Nathan to help with certain business matters while I was overwhelmed with hospital visits and funeral arrangements.
He was supposed to wind everything down.
Instead, he kept handling the account.
“Has he stolen money from me?” I ask.
Denise hesitates.
“I can’t make that determination. But those reimbursement descriptions don’t match the records I was shown.”
I thank her and ask for copies of everything she’s legally permitted to provide.
After she leaves, I sit at the kitchen table with Walter’s notebook open in front of me.
On page forty-six, beneath an entry about replacing a compressor for a customer on Marlowe Avenue, Walter has written a reminder.
Final installment expected in September.
That installment is one of the payments on Denise’s list.
I call our longtime accountant, Mr. Hensley.
He’s semi-retired now, but he agrees to meet me at his little office behind the pharmacy on Westbrook Street.
I bring Walter’s notebook, the old authorization, and the information Denise gave me.
Mr. Hensley reviews the material carefully.
He warns me that we need official bank statements and complete business records before drawing conclusions.
Then he finds something useful.
The account is still legally associated with the old business, and I’m the person responsible for administering its remaining affairs.
Nathan’s authority is limited.
“He can assist you,” Mr. Hensley says. “He cannot simply treat these funds as his own.”
Over the next ten days, I obtain the records, revoke Nathan’s authorization, and arrange for the remaining business obligations to be reviewed.
The discrepancies total a little over thirty-one thousand dollars.
Some payments cover genuine expenses connected with Walter’s old business.
Others went into Nathan’s landscaping operation without my knowledge or approval.
When I finally confront him, he doesn’t deny moving the money.
He sits on my sofa with his work boots planted on the rug and insists he always intended to replace it.
“I was keeping my business alive, Mom.”
“With money you didn’t tell me you were using.”
“It was Dad’s business. I figured you’d want me to keep things going.”
“Your father wanted that business closed properly.”
Nathan rubs his forehead.
Then he says something that hurts worse than the financial discovery.
“You don’t understand what it’s like having people depend on you.”
I look at him.
“I raised three children, Nathan.”
He doesn’t answer.
When I tell him I’ve removed his access to the account, he stands up.
“So that’s it? You’re choosing money over your own son?”
“No. I’m asking you to be accountable for what you’ve done.”
He leaves without saying goodbye.
Brooke calls that evening.
Apparently, Nathan has told her I’m trying to destroy his business.
Colin sends me a message saying I’m being unnecessarily harsh.
Neither asks to see the records.
I don’t argue.
I arrange for an attorney to help resolve the missing funds and the remaining business obligations.
The process isn’t pleasant.
Nathan has to provide financial records and agree to a repayment arrangement after the accounts are reconciled.
I no longer lend money to any of my children.
For a while, that means I hardly hear from them.
Then something unexpected happens.
Lily calls me from her mother’s phone.
She’s upset because she only recently learns I was told not to attend her graduation.
“Dad said you were sick.”
I close my eyes.
“I’m sorry I missed it, sweetheart.”
“Did you get my invitation?”
“It’s still on my refrigerator.”
There’s a pause.
Then she asks whether she can come over on Saturday.
I say yes.
When she arrives, she’s carrying her graduation gown in a wrinkled grocery bag and a small photograph taken outside the school auditorium.
She puts the photograph beside Walter’s notebook.
“Mom said you should have one.”
I make grilled cheese sandwiches, and we sit at the kitchen table talking about her plans for community college.
Before leaving, Lily asks why Nathan is angry with me.
I tell her that her father and I disagree about some money, and that it’s something the adults need to work out.
She seems relieved that I’m not asking her to take sides.
A few months later, Nathan begins making the agreed payments.
Our conversations remain awkward and short.
I don’t pretend everything is repaired simply because a check arrives.
But one Sunday, he calls and asks whether he can help replace the loose railing on my back steps.
I tell him I’ve already hired someone.
He sounds disappointed.
Then he asks how Lily’s classes are going.
We talk for twelve minutes without mentioning a single bill.
After hanging up, I take the blue graduation invitation down from the refrigerator. I put it in the drawer with Lily’s photograph and the little thank-you card she sent after our lunch.
The strawberry magnet goes back on the refrigerator.
I use it to hold up the grocery list.